Thinking about buying or selling in La Quinta but unsure where to start? You’re not alone. The desert’s resort energy, seasonal patterns, and HOA rules make this market feel different from most places in California. In a few minutes, you’ll understand how La Quinta works, what drives value, and the smart steps to take next.
Let’s dive in.
Why La Quinta draws buyers
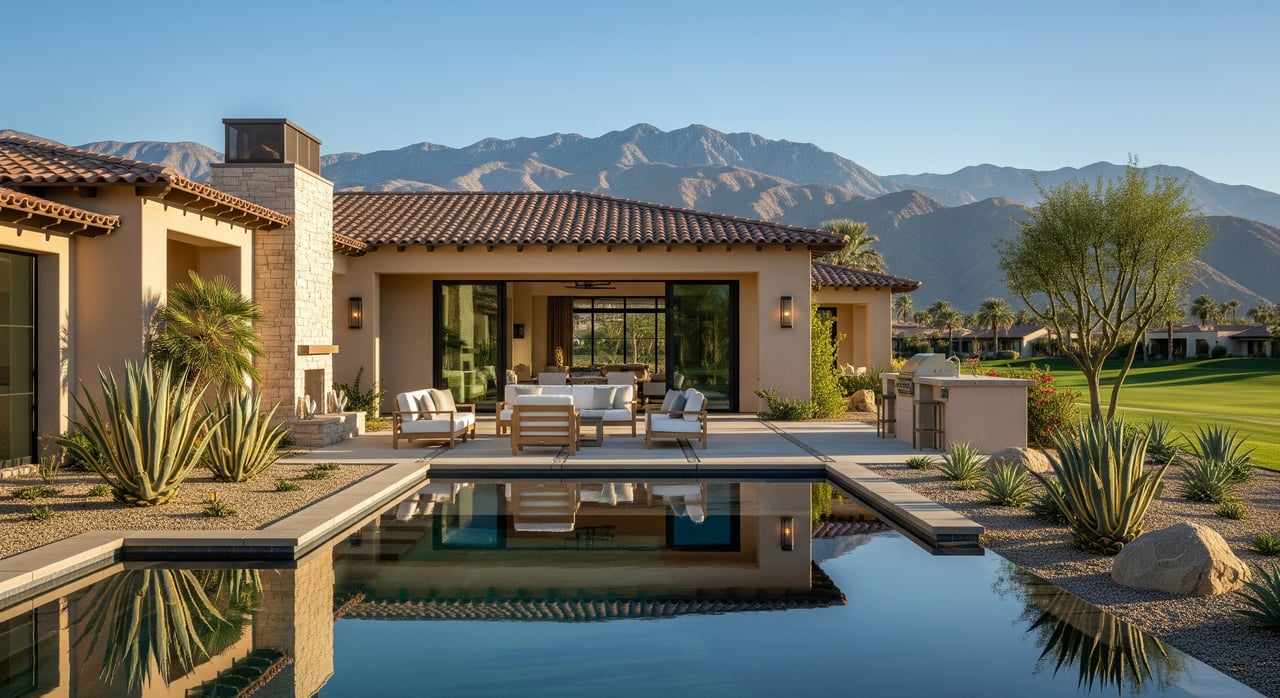
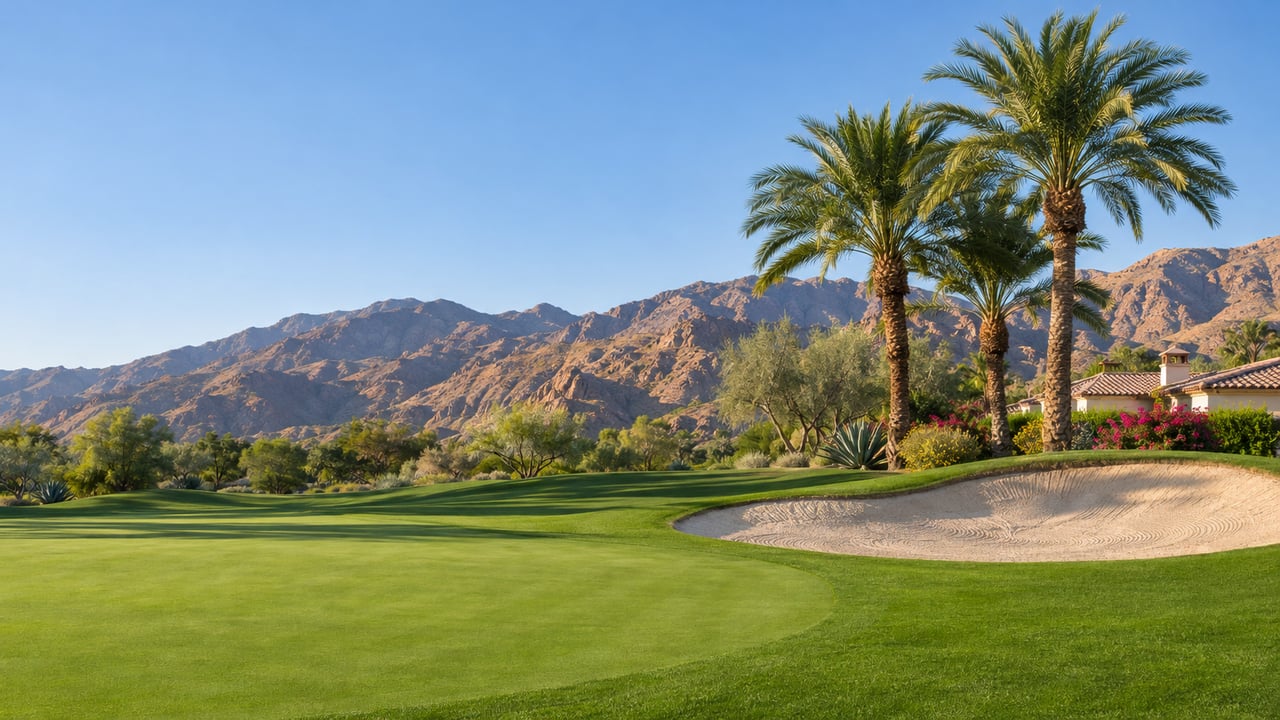
La Quinta sits in the eastern Coachella Valley in Riverside County, near Palm Springs, Indian Wells, Rancho Mirage, and Indio. The area’s reputation for golf, wellness resorts, and dramatic mountain views shapes both demand and inventory.
Many buyers arrive as retirees, second-home owners, or seasonal “snowbirds.” Others are local professionals or investors who value a resort lifestyle and strong amenities. Sellers often include downsizers, investors, and owners who time listings for peak winter traffic.
Seasonality and timing
La Quinta follows a clear seasonal rhythm. Buyer activity typically surges from late fall through spring, roughly November to April, when weather is mild and many out-of-area buyers are in town. The hottest months bring fewer showings, so some sellers delay listing until the cool season.
What that means for you:
- Buyers: Expect more competition and faster decision cycles in winter. Off-season can offer more negotiation room, but inventory and open houses may be limited.
- Sellers: High season brings more eyes on your home. Early spring often sees more new listings, which can increase buyer choice and comparison shopping.
What’s on the market
La Quinta offers a wide mix of property types:
- Single-family homes, including golf-course and mountain-view lots.
- Condos and townhomes, often in gated settings.
- Resort-style and custom luxury estates inside guard-gated communities.
- 55-plus and active adult developments.
Because this is a resort market, you’ll see a higher share of second homes, HOA-governed communities, and cash purchases than in many inland markets. New construction appears intermittently and may include Mello-Roos special taxes in newer subdivisions.
Price tiers and value drivers
Rather than fixating on static price points, think in value tiers that move with market conditions:
- Entry tier: Condos, townhomes, and select smaller single-family homes. These often appeal to first-time buyers, local professionals, and part-time residents.
- Mid-market: Traditional single-family homes on modest lots. A mix of original-condition properties and homes with thoughtful updates.
- Upper tier: Guard-gated, golf-community, and custom hillside estates with premium views, pools, and high-end finishes. These often attract second-home buyers and cash purchasers.
Key value drivers in La Quinta include view premiums, lot size and position, quality of upgrades, outdoor living spaces and pools, proximity to Old Town amenities, access to resort or club facilities, and whether golf memberships are transferable. When you evaluate options, focus on setting, architecture, and livability rather than only square footage.
HOAs and community rules
HOAs are common in La Quinta and shape daily life and ownership costs.
- HOA defined: A homeowners association manages common areas, amenities, and community standards. Monthly dues vary based on services and amenities.
- CC&Rs: Covenants, Conditions and Restrictions are the binding rules of the community. Review them to understand architectural standards, rental policies, and use restrictions.
- Legal framework: California’s Davis-Stirling Common Interest Development Act governs HOA operations, disclosures, reserve studies, and meeting procedures.
- Buyer due diligence: Ask for the resale certificate and the full disclosure packet. Read the CC&Rs, bylaws, recent financials, reserve study, board meeting minutes, and any notices about planned assessments or litigation.
- Fees and assessments: Dues can range widely. Amenities like staffed gates, landscaping, golf, tennis or pickleball, and clubhouses tend to increase costs. Check reserve strength and the history of special assessments.
Short-term rentals: Vacation rentals exist in parts of La Quinta but operate under city registration, transient occupancy taxes, and community-level rules. Many HOAs restrict or prohibit short-term rentals. Policies evolve, so verify city requirements and your HOA’s rules before you buy or list.
Financing considerations: Lenders may have specific approval standards for condos and HOAs. Rental caps or litigation can affect loan options. If you plan a second home or investment purchase, confirm both HOA and lender criteria early.
Taxes, financing, and insurance
- Property taxes: In California, Proposition 13 generally caps annual assessed value growth at 2 percent for existing owners. Properties are reassessed to market value upon a change of ownership or new construction. Some newer communities carry Mello-Roos community facilities district taxes or other special assessments.
- Buyer types: Cash buyers are common in second-home and luxury tiers. Conventional financing is typical for primary residences. Jumbo loans are frequent for higher-priced homes. Second-home loans include added underwriting on occupancy and reserves.
- Insurance: Standard homeowners policies are the baseline. Evaluate flood risk using official maps and consider earthquake coverage based on your risk tolerance. Premiums and coverage availability can vary by region.
Neighborhood types at a glance
Every neighborhood tells a different story. Here are common patterns you’ll see across La Quinta:
- Guard-gated golf communities: Staffed gates, club amenities, fairway and mountain views, and elevated price points. Some include membership options with transfer rules.
- Resort-adjacent enclaves: Homes near resort golf or spa amenities without being inside the resort’s gates. These often balance access with lower dues.
- Old Town and walkable areas: Proximity to dining, boutiques, and community events. These suit buyers who prefer convenience over large lots.
- Cove and smaller enclaves: A range of single-family homes and townhomes on smaller lots, often with scenic backdrops and varying HOA structures.
When comparing areas, consider travel time to Highway 111 and Interstate 10, club access, view corridors, and whether Mello-Roos or special assessments apply.
Timing your move
There is no single best month that fits every goal. If you’re selling a view-rich or amenity-driven property, listing in peak season can offer more qualified foot traffic. If you’re buying and want a slower pace, late spring or summer may present chances to negotiate, though inventory may be tighter.
Use current local reports for the latest month-to-month shifts. Because inventory, days on market, and list-to-sale ratios adjust through the year, lean on up-to-date neighborhood data before setting price or timing.
Smart prep checklists
Buyer checklist
- Define your occupancy: primary residence, second home, or investment.
- Set a full budget that includes HOA dues, property taxes, insurance, and utilities.
- Decide where amenities rank against view, privacy, and architecture.
- Get pre-approved, and discuss jumbo or second-home guidelines with your lender.
- Review HOA health: reserves, assessments, rental policies, and litigation.
- Confirm any short-term rental plans comply with city and HOA rules.
- Price your offer to the micro-market: street, view corridor, and condition.
Seller checklist
- Identify your value drivers: views, lot position, upgrades, outdoor spaces.
- Refresh the home: paint touch-ups, landscape tune-ups, and minor repairs.
- Assemble documents early: HOA disclosures, recent improvements, permits, and any club or membership details.
- Time your launch: align listing prep with photography and high-season exposure.
- Price to the data: compare most recent neighborhood sales, not only citywide figures.
- Plan for showings and seasonal travel schedules of likely buyers.
Definitions you’ll hear
- HOA: Organization that manages common areas, amenities, and community standards.
- CC&Rs: The rules that govern what owners can and cannot do in the community.
- Mello-Roos or CFD: A special tax used to repay bonds for public improvements in newer areas.
- Guard-gated vs gated: Guard-gated has staffed security checkpoints; gated may have restricted access without staff.
- Resale certificate: HOA disclosures that include finances, rules, and other required information for buyers.
- Primary residence vs second home vs investment: Occupancy types with different financing, tax, and rental implications.
How we can help
If you are navigating a guard-gated or golf community, a second-home purchase, or a complex sale with entity structures or club memberships, experienced guidance matters. You get discreet, design-aware advice, careful document review, and a strategy shaped to your goals and the season.
Ready to talk through your plan and the latest neighborhood data? Schedule a confidential consultation with Unknown Company.
FAQs
When is the best time to buy or sell in La Quinta?
- Winter typically brings the most buyer activity, while spring often adds new listings. Off-season can offer calmer negotiations. Base timing on current local stats.
How do HOA fees affect affordability in La Quinta?
- HOA dues add to monthly costs and vary with amenities. Review dues, reserves, and any pending special assessments when calculating your budget.
Are short-term rentals allowed in La Quinta neighborhoods?
- It depends on both city rules and the HOA. Some areas permit registered vacation rentals, while many HOAs restrict or prohibit them. Always verify before you buy.
Do many La Quinta homes sell for cash?
- Yes, cash is more common here than in many non-resort markets, especially in the luxury and second-home tiers. The exact share varies by season and price band.
Are there extra taxes beyond base property tax?
- Some newer communities have Mello-Roos or other special assessments. Check the tax roll and your preliminary title report for precise amounts.
What should I review in HOA documents before buying?
- Read the CC&Rs, bylaws, financials, reserve study, recent meeting minutes, rental rules, delinquency rates, and any notices of litigation or planned assessments.
How do loans differ for second homes or condos?
- Lenders may require added reserves and documentation for second homes. Condos can have HOA approval requirements, and rental rules may affect loan options.